APPLICATIONS vs INFRASTRUCTURE
My thoughts on this never-ending debate
Over the past few weeks, through tweets, articles, and podcasts, I have seen many people lamenting the underinvestment in applications compared to infrastructure, particularly at the private early stage.
This mini article provides my take on this well-known debate and why I believe this phenomenon is normal and likely to persist.
The lack of investment in the app layer is leading people to believe this is why we do not have more apps with Product Market Fit (PMF). Additionally, we are not seeing significant "infra fatigue" in valuations either compared to apps. I think there are a few reasons for this.
Let’s start by stating the obvious, VCs are not non-profits; they are not going to fund apps just for the goodwill of the space or for people to have more apps to play with. The reality is that infrastructure trades 5x to 10x higher on liquid markets, which naturally pushes VCs to continue investing in infra at higher valuations than apps. But why? I think there are four main reasons that explain this:
1. Looser Metrics and Timelines: The metrics and timelines for evaluating infra investments are much looser compared to apps.
2. Scarcity of Revenue-Generating Apps: Apps with substantial revenue continue to be scarce.
3. Uncertain Value Accrual: The value accrual mechanisms at the app layer are not embedded and are uncertain.
4. Uncertain PMF for several Verticals: PMF for several app verticals remains very uncertain and may not align with overall industry growth.
On Looser Metrics and Timelines
When you invest in an app, the metrics used to judge its PMF, or value are very tangible. You can easily measure its traction through metrics such as daily active users (DAU), volume, revenue, fees, Active addresses, total value locked (TVL), etc. These metrics are consistent across competitors, and the app usually depends less on other protocols to be able to prove its value (except for some integrations).
In contrast, when you invest in infrastructure, you rely on other apps and protocols to use your technology, regardless of who they are. The risk you are underwriting is much lower in my opinion. For example, if you invest in @TraderJoe_xyz, you are betting on it becoming the dominant DEX, competing with about 25 other DEXes on similar metrics. It becomes apparent quickly if it is one of the best solutions available.
If you invest in @avax, you are betting that someone will pay for the blockspace it produces. It doesn't matter whether it's @TraderJoe_xyz, other competitors, a DEX, or a game—the bet is much broader. Additionally, your user base consists of developers, meaning the sales and onboarding cycle is much longer than direct-to-consumer, allowing more time for the investment thesis to play out and for the project to partially pivot. Since these tokens are liquid from the start, VCs are aware of this and factor it into their investment considerations.
In my opinion, many infra bets are easier to underwrite. Betting on more cross-chain transactions? Invest in bridges. More DEXes or money markets needing price feeds? Invest in oracles. More roll-ups being built? Invest in RaaS providers. You are essentially betting on the growth of the space, and generally, the metrics and timelines are much looser than for apps.
The best example of this is Layer 1 (L1) blockchains. The metrics by which we measure L1 PMF and valuations are still highly uncertain and subject to debate. If you look at the space right now, the metrics vary significantly:
- @NEARProtocol: Most Daily Active Users (DAU)
- @solana: Most daily transactions (Tx)
- @ethereum: Most Total Value Locked (TVL) and DEX volume
- @trondao: Most Active Addresses
- @CelestiaOrg: Cheapest data availability (DA)
We still debate to this day why one L1 is better or more widely used than another. This type of debate doesn’t happen at the app layer, providing VCs with a greater margin for error.
On Scarcity of Revenue-Generating Apps
The reality is that there are not many apps generating millions, let alone tens of millions, in monthly revenue. As the industry matures, this has spooked investors historically. If we look at the top 10 revenue-generating apps right now (per @DefiLlama) , almost all are infrastructure-focused.
There are really 4 apps that you could argue are somewhat consumer (but they aren’t really in my mind) in that top 10: A couple of DEXes (@Uniswap and @RaydiumProtocol), one money market (@aave), and one launchpad/Exchange (pump.fun). Notably, none of these accrue value to their token holders.
Note that for apps like @Uniswap, where fee sharing with token holders has been discussed in the past, most of the fees generated will go to LPs. The potential revenue for token holders as seen in recent forum discussions is likely to be 0.05% out of the 0.3% that goes to LPs, meaning only 1/6 of the fees generated would accrue to token holders, and only in specific pools.
The ability for apps to generate substantial revenue and accrue value remains uncertain. It's important to understand that most of the fees and revenue in crypto are accrued at the infrastructure layer.
Among all the metaverse games, NFT products, and social apps funded in the last four years, how many of them have generated consistent revenue?
When we start seeing multiple apps generating over $5M-$10M USD in monthly revenue, the dynamics may change, but this is something we have yet to witness.
On Uncertain Value Accrual
Like revenue, the question of how many apps accrue value to token holders remains critical. The famous "Wen fee switch?" is still largely unanswered. There is no clear path to making this happen at the app layer, whereas for L1, L2, or other infra protocols, fees and MEV are embedded into the protocol. The mechanisms for value accrual for validators, sequencers, and relayers are well-known and effective. Staking the token, delegating to a validator set, or holding a Liquid Staking Derivative (LSD) while receiving MEV and priority fees provides embedded value accrual that does not require additional engineering or governance approvals. This effectively solves the problem of valueless governance tokens.
Of the four apps mentioned earlier in the top 10, only @Uniswap has the potential to distribute revenue to token holders, and it recently received a Wells notice from the SEC, potentially due to the UNI token being considered a security. Embedding value accrual into a token that is not used to decentralize and operate a validator set remains a significant challenge for teams.
Furthermore, from a fundraising perspective, the dual equity and token structures some protocols use are not optimal for VCs and exit opportunities. If you invest in a game but not in the company building it, or vice versa, complications arise if the company launches another game with a new token. We just lack examples of such company structures being successful exits for VCs.
We haven't seen enough venture-scale outcomes at the application layer, especially for consumer apps. In the top 100 on @coingecko, the only real consumer app is probably @AxieInfinity, worth $1.6B USD. This is a good outcome for pre-seed and seed investors, or anyone who sold at the peak, but if you look at the token chart and the game's metrics, it's clear this isn't what success looks like.
What examples do we have from past cycles? @TheSandboxGame? @apecoin? @opensea? The most represented consumer apps in the top 100 are really meme coins if you think about it (@dogecoin, @Shibtoken, @pepe, @bonk_inu, Wif), which are not VC investable, at least for now.
This app vs. infra debate is not a secret; apps are aware of it, and many want to transition to infra plays. The same goes for value accrual and revenue. This is why we see more apps deploying their own app-chains (@dYdX), app-specific roll-ups (@aevoxyz), or generalized L1s. @Uniswap is going both deeper and higher into the transaction supply chain, developing its own wallet and launching a browser extension to reduce dependency on other wallets and order flows. Uniswap X relies on its own fillers/solvers, aiming to rebate as much MEV back to the user/app layer.
Similarly, @dYdX with its own app-chain allows validators to accrue fees and token holders to benefit from direct fee distribution. They now have full control over their blockspace, allowing them to subsidize gas, make low level protocol tweaks, or increase throughput as needed.
I believe these blue-chip apps owning more of the underlying infra will start to command a premium in the long run, especially compared to vanilla apps without underlying tech ownership. Valuations will likely adjust accordingly. @MakerDAO and @aave have plans to build their own execution environments. Even on @solana, teams like @ZetaMarkets are building their own L2 solutions, which, while primarily for performance reasons, will leverage their token and tech stack differently than if built on @solana L1.
On Uncertain PMF
I agree that crypto markets are still relatively inefficient compared to traditional finance markets, but I don't believe they are *that* inefficient. I still subscribe to the efficient market hypothesis to some extent.
Why have we funded 40 different teams building bridges? Why haven't we seen 30 copycats of @farcaster_xyz being funded yet?
Right now, there are three things that have found true PMF in crypto:
1. Rules-based money or store of value: @Bitcoin
2. Stablecoins: USDT, USDC, DAI
3. Blockspace: @ethereum , @solana , etc.
Anyone claiming otherwise is likely overstating the case or the protocol/app is heavily incentivized.
So, the question many are asking is this: Could we see a 10x increase in activity and usage of crypto in the next three years without a couple of bridges, money markets, or DEXes accruing a lot of value and 10xing their activity? The chances are extremely low.
Can we say the same for socialFi or GameFi? Not really. This is the crux of the matter, in my opinion. Some direct-to-consumer verticals could remain niche while the space grows 10x and finds mass adoption in areas we *know* have PMF.
At the end of the day, storing, moving, and preserving the value of money are things crypto is extremely good at. Will we have a TikTok-like socialFi app with 500M DAUs? It seems VCs are not willing to bet on that just yet, and they aren't totally off base.
One last point worth mentioning regarding Layer 1 blockchains is their critical role as reserve asset for VCs. The vast majority of the capital in our industry enters through early-stage private markets, and L1s play a significant role in this process.
Often, when VCs raise funds and are not quite ready to start deploying, they often begin by investing in the underlying L1, this allows them to get overall market performance before actually allocating capital to private deals. This strategy allows them to have market beta while the capital is still largely undeployed.
Conversely, VCs may liquidate lower and mid-tier performers and consolidate their investments back into the underlying L1 when they anticipate favorable market conditions. These dynamics result in L1s often being treated as reserve assets, experiencing substantial passive flows that applications do not typically receive.
This is now more prevalent than ever given every VC has a liquid side pocket and every liquid fund has an early-stage side pocket.
Coming back to our conversation. I am bullish on several verticals where I think we will see apps taking off and gaining significant traction, but the underinvestment in the app layer and its discount compared to infra is more than justified, in my opinion.
Thinking we will stop investing in L1s, zk-tech, shared sequencing, etc., is absurd. Investing in cheaper, more efficient, more decentralized, and scalable blockspace is essential, and the demand for it will continue to grow exponentially.


 Cathie Wood
@CathieDWood

 Voyager
@voyagertrader
 Tasha Keeney


 Brett Winton

 Aaron Burnett
 Morgan Brennan
 Tarek Mansour


 Joby Aviation
 Nick Grous
 Sam Korus
 Daniel Maguire


 ARK Funds
 Rahul Bhushan

 Goshawk Trades


 Larry Goldberg
 Shiv Verma

 Frank Downing


 Karim Mattar


 Lorenzo Valente

 Brian Roemmele


 Liz Ann Sonders
 @jason

 Naveen Rao


 Gavin Baker


 Podcast Alpha
 Matthew Elliott

 dash

 Shay Boloor


 Varshika Prasanna
 Cute Baby


 Tom Wan

 John Bistline


 Nic Cruz Patane
 James Wang

 Radiant


 Alex


 Arthur MacWaters

 Liz Thomas


 Finney Foundation for Open Technology


 Tibo

 Chase Prather


 Raye Hadi
 David Puell

 Austin Koring


 Dustin


 Eleanor Terrett


 Shaun Maguire
 Brad Gerstner

 Crypto Intel
 Macro Bombastic
 Keith Tsang
 FINMAN


 𝘽𝙤𝙗𝙗𝙮 𝙃𝙚𝙖𝙡𝙮

 JoshWest247 ⚡️


 Vlad Saigau


 Artificial Analysis


 spARK Labs by ARK Invest


 Ian Miles Cheong
 Amjad Masad


 Shanaka Anslem Perera ⚡


 Akshay Krishnaswamy

 Refik Anadol


 Shea Wihlborg


 Captain Eli


 LayerZero

 anand iyer


 Canton Network


 Keenan


 Eve 异野夕 w/ 异の泡泡针


 TBPN


 steven epstein father of 2 great kids




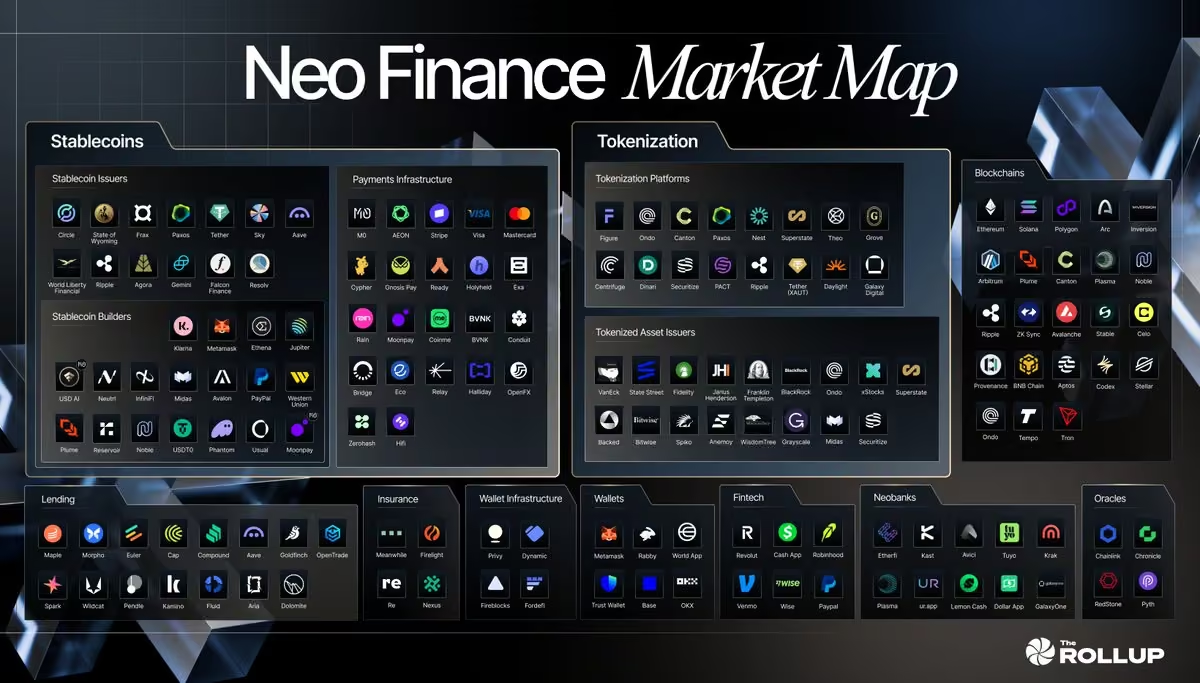
 The Rollup
 Brian Armstrong


 X Freeze


 David Moss


 eMerge Americas

 binji

 Francis B. Zhou


 ALEX


 ARK Invest Europe


 Charles Roberts

 Eric Balchunas

 Zack


 Adrian Dittmann


 Wilfred Frost

 Tim Urban

 Bill Gurley


 Bitcoin Park



 Sawyer Merritt




 NeoSam
 AJ Investment Research


 Nick Sortor


 Barnesy Health

 Ramez Naam


 U.S. FDA


 Ovid C. Amadi


 KanekoaTheGreat

 The Bitcoin Office


 Archer


 Yair Einhorn
 Arthur B. Laffer
 Gene Investing w/Anthony 🧬


 Keller Cliffton




 Fay Arjomandi


 Brett Adcock

 Digital Asset Summit 2026


 U.S. Senator John Fetterman

 Dave Lee
 build the bridge


 GREG ISENBERG

 Penn Blockchain

 The Kobeissi Letter


 America

 Tesla Super Intelligence
 Jared Friedman

 Diario El Salvador

 Joe Portman

 DogeDesigner


 Yassine Elmandjra

 Jeff Sheehan Author | Mktg Consultant | Speaker

 Alex Immerman

 Katherine Boyle


 Milan Kovac


 Lyn Alden

 Farzad 🇺🇸 🇮🇷


 Jeremy Wayne Tate

 IMPERATOR
 Dalton Brewer


 Consensus by CoinDesk

 Max Keiser


 Marko Bjegovic

 E.J. Antoni, Ph.D.


 Steve Jurvetson


 Cognition

 Jamin Ball
